

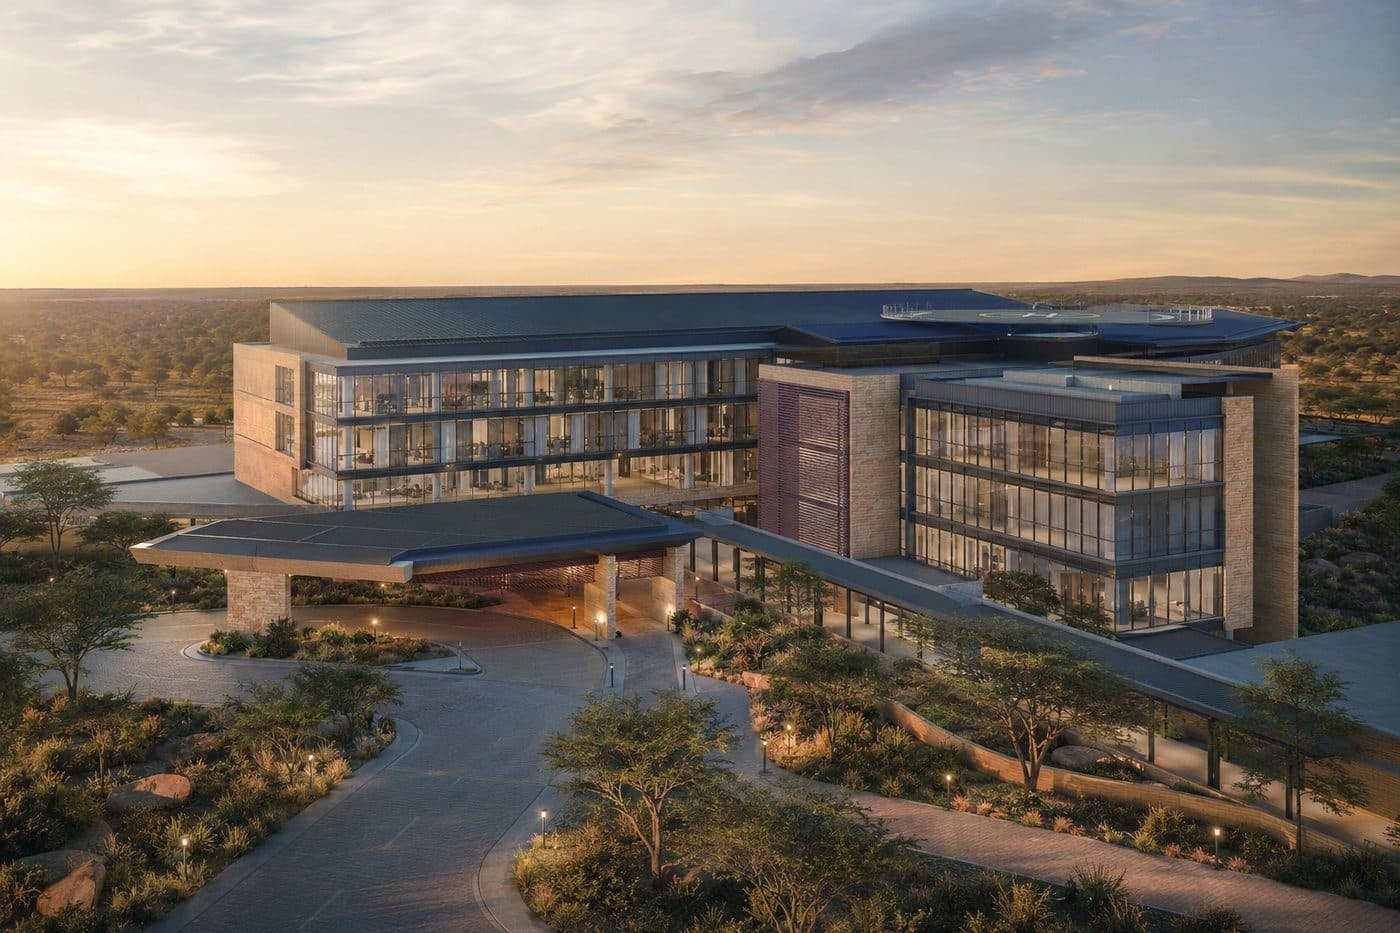
Care the whole region can reach, and an export Botswana earns from.
TEMCO is a 130-bed hospital at the Sir Seretse Khama International Airport Special Economic Zone, planned to open in 2029 and built to be the best specialist hospital in southern Africa. Every patient who lands in Gaborone instead of leaving is foreign exchange earned, and the capital structure behind the hospital is open to your proposal.
The Opportunity
Under one roof it holds the range of care a major hospital provides, and above that the complex work that currently takes families out of the region altogether: high-risk maternity and neonatal intensive care for newborn babies, children's surgery, fertility, gynaecological cancers of the cervix and ovaries, and structural heart. The hospital sits inside Botswana's own development agenda. It is a Healthcare Entry Point Project under the country's Economic Transformation Programme and an NDP 12 priority, and it carries BETP Secretariat delivery-readiness validation together with a Ministry of Health Letter of Support.
Debt, equity, blended, convertible or a joint venture: the structure is yours to propose, and the project economics hold across each. On the revenue side the hospital earns on both flows, with regional patients paying in hard currency and Batswana treated at home no longer exporting the spend.
Built for institutional capital and delivery partners
TEMCO is structured around two partnerships, one for senior institutional capital and one for international construction delivery, with the build designed to be de-risked from the outset.
Senior Capital
Institutional capital partnership
The senior tranche of the raise — institutional capital bringing private-equity diligence and structuring discipline to the project.
Construction & Delivery
International construction-delivery partnership
International build capacity with capital aligned to delivery — designed to de-risk the construction programme through to commissioning.
Engagement is by invitation, in conversation — the capital structure is open to investor proposal, agreed at partnership formation.
130
Specialist Beds
SSKIA
SEZ Location
25 Yr
Operating Model
2029
Target Opening
Why TEMCO
Inside the National Agenda
TEMCO is a Healthcare Entry Point Project under Botswana's Economic Transformation Programme, an NDP 12 priority, with BETP Secretariat delivery-readiness validation and a Ministry of Health Letter of Support. The country has written this hospital into its own plan for the decade.
Healthcare as a National Export
Families across southern Africa already pay for specialist treatment abroad, in hard currency, and that spending leaves the region entirely. TEMCO is built to bring a national-scale share of it to Gaborone, where it becomes export earnings for Botswana alongside the everyday specialist access it gives Batswana through public referral, medical aid and private cover.
Two Patient Streams
The hospital serves the region first and Botswana alongside it. Complex and specialist cases fly in from across SADC and beyond and pay in hard currency, which is the export core, while Batswana reach the same theatres, the same scanners and the same neonatal cots through public referral, medical aid and private cover. The base is regional demand plus broad local access, which spreads the hospital's income across two populations and two payment routes.
An Airport-Adjacent Fiscal Footing
TEMCO stands inside the Sir Seretse Khama International Airport Special Economic Zone, which carries 0% customs duty on qualifying medical equipment, free profit repatriation with no exchange controls, SEZA-serviced land, licence validity of up to 50 years and no export mandate. Most of the region is inside a 90-minute flight of the front door.
Seven advantages, and each one holds when the others are tested
No single advantage carries the project; seven do, and they reinforce one another. Select any one to read what it means.
Advantage 01 of 07
Specialist care at a regional price
Specialist procedures are priced 25–35% below South African private rates, and for most of the region Gaborone is about ninety minutes in the air, so a family funds neither the premium nor the long transfer that treatment abroad adds on top of the operation itself. The standard of care behind that price is held to an internationally accredited pathway.
Advantage 02 of 07
Terms inside the airport zone
The hospital is built inside the Sir Seretse Khama International Airport Special Economic Zone, which carries 0% customs duty on qualifying medical equipment, free repatriation of profit, no exchange controls, serviced land from SEZA and a licence valid for up to fifty years. Nothing in that licence obliges the project to export, so patients flying in and Batswana at home are treated in the same building on the same terms.
Advantage 03 of 07
Built for the whole region
Direct flights reach the airport from Johannesburg, Cape Town, Addis Ababa, Lusaka and Harare, putting a catchment measured in countries within a short drive of the ward doors. A patient and the relative travelling with them spend roughly half what the same trip to Bengaluru or Bangkok costs, before a single procedure has been booked.
Advantage 04 of 07
Inside the national programme
TEMCO is a Healthcare Entry Point Project under Botswana's Economic Transformation Programme and a priority under NDP 12, with delivery readiness validated by the BETP Secretariat and a Letter of Support from the Ministry of Health. The country is building the hospital as an export the way it built tourism, and the delivery reporting runs through the national programme itself.
Advantage 05 of 07
Clinical partnership and the JCI pathway
A clinical operations partner anchors the protocols, the staffing pipeline and the training that holds them together. The hospital is designed to the Joint Commission International accreditation pathway from the day it opens, so the standard is built into the equipment, the rosters and the record-keeping before the first patient is admitted.
Advantage 06 of 07
A steady place to be treated
Botswana is an investment-grade sovereign (S&P BBB-, Moody's Baa1, both on negative outlook as of October 2025), with an independent judiciary, common law and English as the official language. When a family sends a relative across a border for surgery, that steadiness is part of what they are buying, and it is why referrers across the region can plan around a hospital here.
Advantage 07 of 07
The full range, and the tier above it
TEMCO is built to carry everything a major general hospital provides and, above that, the complex work that currently sends patients out of the region altogether: two-linac radiation oncology with IMRT/VMAT/SBRT/SRS and HDR brachytherapy, structural-heart intervention (TAVR, MitraClip, LAA closure), complex 3D-mapping electrophysiology, PET/CT imaging, and the first robotic-assisted surgical platform in Botswana. Maternity and high-risk pregnancy care (obstetrics) stand beside neonatal and paediatric intensive care for newborn babies and children, with IVF and fertility medicine for women and for men, surgery for gynaecological cancers of the cervix and ovaries, and children's surgery under the same roof, so a mother in difficulty and her newborn are cared for by one team. Every one of these services opens in 2029.
Investment Profile
A qualitative read on the project's return profile, built on a full 25-year financial model spanning capital structure, detailed return metrics and sensitivity analysis.
Above Hurdle
Project Returns
Material project IRR above the cost-of-capital hurdle in the base case
Long-Dated
Return Profile
25-year operating horizon with meaningful terminal value
Within a Decade
Payback
Payback achieved within the first decade of operations
Positive
Net Present Value
Positive NPV at the base-case discount rate
Strong
Operating Margins
Strong stabilised EBITDA margin at steady state
Open
Capital Structure
No pre-specified debt/equity mix — investor proposes
The return profile is long-dated and asset-backed, modelled over a 25-year operating horizon.
Strategic Influence
Board representation and an operating role on the development team for partners who want one — board seat or observer rights, with your sector advisors invited onto the team. Governance and involvement are defined at the partnership level.
25-Year Financial Model
The project is underpinned by a detailed 25-year unlevered financial model, with a conservative occupancy ramp that reaches steady state over three years, strong EBITDA margins at maturity and meaningful terminal value.
Upside scenarios (additional SADC inbound capture, medical tourism step-up, pharmaceutical Phase 2) are documented but not relied upon in the base case.
What a private review covers
- Revenue build by service line and year
- EBITDA build with full cost-base assumptions
- Capex schedule with equipment lease treatment
- NPV, IRR, payback and sensitivity analysis
- Terminal value scenarios and exit pathways
- Downside stress testing and breakeven analysis
We walk strategic partners through the model directly, in a working session. It begins with a conversation.
No mother should have to cross a continent to keep her child alive.
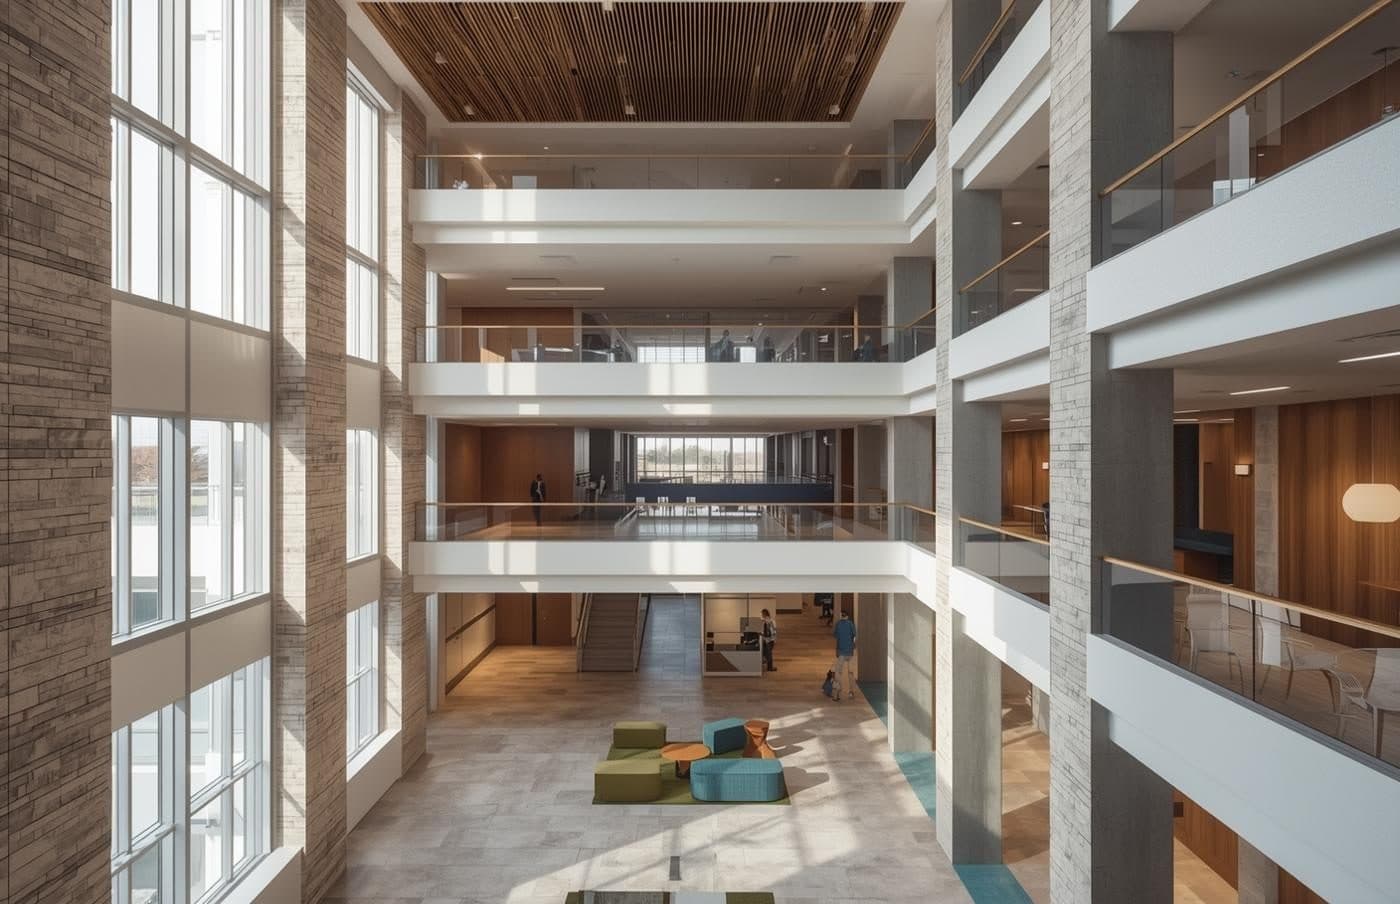
Indicative architectural design concept — TEMCO Specialised General Hospital, SSKIA SEZ. Not a photograph of a built facility. Opening 2029.
Addressable Market
TEMCO's primary market is the region. Across 16 SADC countries and a population above 380 million, cross-border referral for specialist care is a multi-billion-dollar flow paid in hard currency, and it sits inside a far larger private tertiary-care market that keeps growing. TEMCO is built to take a national-scale, export-earning share of it, and the floor beneath that is broad specialist access for Batswana together with the complex cases that currently leave the country for treatment abroad.
Picture a woman in Lusaka, thirty weeks into a twin pregnancy, told she will need a team that manages high-risk deliveries and a neonatal unit ready to receive both babies. From 2029 she can reach that ninety minutes away in Gaborone instead of twelve hours away in India, be delivered with intensive care on the other side of the door, and be home inside a fortnight, at rates 25 to 35 per cent below South African private benchmarks. The pathway is illustrative, and families across the region make some version of that trip today and pay for it abroad.
Families are paying for this care today, in other countries, which makes the demand a matter of record.
Cost Advantage
TEMCO is planned to deliver specialist tertiary care on an accredited pathway at 25 to 35 per cent below equivalent regional private rates, without the travel and accommodation cost that treatment abroad carries. Quality and price move together here, because the saving comes from where the hospital is built and from the terms the zone gives it.
- 25 to 35 per cent below South African private rates
- No cross-border travel or accommodation cost
- SSKIA SEZ framework underpins project economics
Accredited-pathway quality at a price the region can reach without leaving it.
Government-Programme Endorsements
NDP 12 Priority
National Development Plan
BETP Project
Economic Transformation Programme
BETP Secretariat Validation
Delivery-readiness validation
SEZ Licensed
Special Economic Zone Authority
Ministry of Health
Letter of Support
JCI Accreditation PathwayTarget
On the accreditation pathway from opening
Investment Timeline
2026
Capital Raise
Investor engagement and financial close
Q4 2026 – Q1 2029
Construction
Build, fit-out and equipment commissioning
Q2 2029+
Operations
Phased ramp to steady-state occupancy
How to Become a TEMCO Capital Partner
A clear five-step process from first contact to financial close. Designed for institutional investors and family offices who require disciplined diligence and structured engagement.
Private Conversation
A direct introduction with the project team. We understand your mandate, share the project thesis, and decide together whether there is a fit worth taking forward.
Working Review
Under mutual confidentiality, we walk you through the financial model, business plan, government-programme endorsements and clinical framework, in a working session.
Site Visit
Visit the SSKIA SEZ site in Gaborone, meet the project team in person, tour the location and speak with government-programme stakeholders.
Term Sheet
An indicative term sheet is exchanged, with the investor proposing structure, amount and conditions, and the negotiation runs around the project economics.
Definitive Documents & Close
Legal due diligence, definitive transaction documents, regulatory approvals and financial close. Construction commences Q4 2026.
Average time from first contact to term sheet: 6–10 weeks. From term sheet to financial close: 12–16 weeks.
What could go wrong, and what we do about it
Every infrastructure project carries risk. Here are the principal ones, named plainly, and the way the project structure answers each.
Risk
Construction & Delivery
The build runs as a phased programme with milestone-triggered drawdowns, delivered by an experienced in-house engineering and architecture team, and independent project monitoring is available to partners who want it.
Risk
Market Demand
The SADC cross-border referral market is a multi-billion-dollar flow that is paid for abroad today, which makes the demand a matter of record. TEMCO is built to hold the complex and rare work inside the region, and the same building carries the everyday specialist load that fills a hospital's beds, so the base does not rest on the rare work alone.
Risk
Regulatory & Political
Botswana is investment grade, rated S&P BBB- and Moody's Baa1, both on negative outlook as of October 2025. It has an independent judiciary, a common-law system, English as an official language, and institutional continuity since independence in 1966. The project is a national-priority development inside the SSKIA Special Economic Zone, which carries zero customs duty on qualifying medical equipment, free profit repatriation and no export condition on the licence.
Risk
Currency & Repatriation
Botswana Pula is one of Africa's most stable currencies — a hard-currency-friendly base for equipment contracts and reference pricing.
Risk
Clinical Recruitment
A clinical operations partner provides protocols, staffing pipelines and training integration. A SADC and international specialist recruitment pipeline is in development, with Botswana-trained specialists supplemented by regional and international hires.
Risk
Capital Structure
The structure is open, so the investor proposes the capital stack. There is no fixed debt requirement, and equity-heavy structures are welcomed for de-risking.
Risk
Operational Execution
A strategic investor with hospital-sector experience is welcome on the operational team, the hospital is on the JCI accreditation pathway, and the pre-operational team is led by registered clinicians and finance professionals.
Risk
Liquidity & Exit
Exit pathways are open, and defined with the partner at formation.
Partner with TEMCO
We engage a small number of strategic partners, chosen carefully. There is no self-serve data room, and the path in is a real conversation with the Chairman's office.
If TEMCO is the kind of asset your institution is built to back, we would welcome the conversation.
Begin a Private ConversationA genuine investor enquiry, answered selectively by the Chairman's office.
Visit Us in Gaborone
Partners we are in conversation with are invited to the SSKIA SEZ site in person — to meet the project team, tour the location and meet government-programme stakeholders. Visits typically run 1–2 days and are coordinated around your travel.
Information herein does not constitute an offer to sell or a solicitation of an offer to buy any security. Any offering will be made only to qualified investors pursuant to definitive transaction documents, in compliance with applicable law. Past performance is not indicative of future results. All projections are based on assumptions that may not be realised. Investors should conduct their own due diligence and seek independent professional advice before making any investment decision. TEMCO Specialised General Hospital is a project of Murua Home (Pty) Ltd, CIPA BW00009159934.